When the bill rate looks simple, but isn’t
The first quote usually arrives as a single number: a bill rate that seems to settle the whole question of labor cost. In the moment, it feels clean—especially when payroll is already overloaded and the role needs to start next week. Then the friction shows up in budgeting: that hourly figure might behave like an all-in price, or it might be just the beginning of a stack of pass-through items that hit later.
What makes it tricky is timing. The bill rate can look stable on day one, but the first month’s invoice often includes line items, minimums, or adjustments that shift your cash-flow plan by a few thousand dollars. Until you know what’s embedded versus billed separately, the “simple” rate is more like a placeholder than a real cost.
Your first assumption: agency handles everything payroll-related
The next move is almost automatic: treat the agency as the “payroll owner,” assume W-2, withholding, and filings are off your plate, and plug the bill rate into the budget as if it already includes every statutory cost. It’s a reasonable assumption when the start date is tight and the internal payroll queue is backed up. The problem is that “handled by the agency” often describes the mechanics, not the economics.
In many arrangements the agency is the employer of record, so it runs payroll, remits withholding, and carries certain policies. But the invoice can still push those costs back to you through a markup, a stated burden rate, or pass-through lines tied to specific jurisdictions. That’s where cash-flow gets awkward: taxes and premiums don’t always track evenly with hours, and corrections can show up a pay period or two later. The first constraint to notice is timing—what you thought was an all-in hourly cost may be an hourly cost plus later reconciliations.
The mismatch appears on the first invoice details
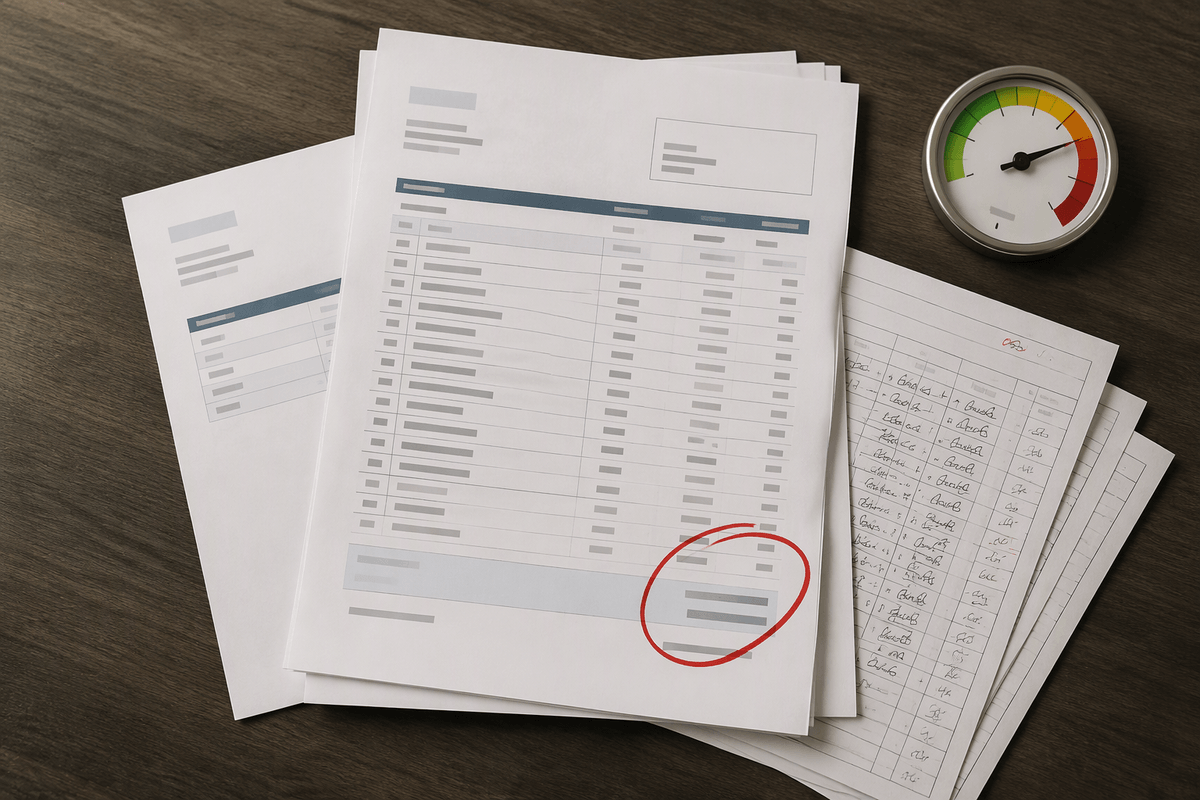
The first invoice is usually where the “all-in” story either holds up or quietly changes shape. The top line may still be the quoted bill rate, but the detail lines start doing the talking: overtime billed at a different multiplier than expected, a separate “statutory” or “payroll tax” line, or a charge that only appears because the worker crossed a weekly hour threshold. If timecards were approved late, the invoice can also land before you’ve reconciled hours internally, which turns a small variance into a cash-flow problem.
It’s not always hidden, just easy to miss when you’re moving fast. A job-code note can shift the workers’ comp class, a “shift differential” can get treated as a pass-through, and mileage or per diem might bypass the markup you assumed was built in. The mismatch isn’t theoretical—it’s the moment you realize the quote was a scenario, and the invoice is the operating reality.
Who pays payroll taxes versus who bears risk
Once the invoice detail stops matching the quote, the next question usually comes fast: “So who’s actually paying the payroll taxes?” In most staffing setups, the agency is the employer of record, so they file and remit withholding, employer payroll taxes, and related filings under their accounts. But that doesn’t automatically mean they’re absorbing the cost. Economically, those taxes are typically embedded in the bill rate, and if something changes—overtime patterns, bonuses, a location change, a different job code—the tax load can shift inside the pricing even if the hourly base wage didn’t.
The more important split is often “who pays” versus “who bears the risk.” Even when the agency funds deposits and signs the filings, contracts can push financial responsibility back to the worksite for timecard accuracy, supervision, and role changes. A late correction, an off-the-books shift premium, or an employee claim can turn into an indemnity argument, not a payroll question. That’s when it matters whether the agreement treats statutory costs as fixed-in-rate or as adjustable pass-throughs, and whether the risk language matches how the work actually runs day to day.
Workers’ comp and unemployment: the surprise cost drivers
By the time the fourth invoice clears, the “statutory” lines start to feel predictable—until someone gets reassigned for a day. A forklift task slips into a role that was priced as general labor, or a light industrial temp gets asked to run deliveries. Nothing about the pay rate changes, but the insurance and unemployment assumptions underneath the bill rate just did. That’s when the bill rate stops being a wage bundle and starts acting like a live model that reacts to job duties, location, and incident history.
Workers’ comp is the loudest swing factor because the class code matters more than the individual. If the agency reclasses the worker after seeing the duties on-site, the cost can be repriced inside the markup or pushed as an adjustment, sometimes retroactive to the start week. Unemployment can bite differently: the agency is usually the account holder, but contracts may let them recover increases tied to claims experience or state rate changes. The constraint is timing—you often learn about the new load only after hours are already worked, when reversing the assignment isn’t an option.
Benefits and paid time: what ‘included’ often hides
After workers’ comp and unemployment settle into the “watch list,” benefits are where the bill rate can start feeling misleading again—because “included” rarely means “flat.” A quote that sounds fully loaded may still be built on eligibility assumptions: no health enrollment, no paid holidays, no sick time accrual, limited tenure. Then a supervisor asks for consistency—“can they work the holiday week?”—and the cost logic quietly changes. Some agencies treat holiday pay and paid sick time as pass-through wages (marked up like regular hours), while others bill them as separate lines that don’t show up until the calendar forces the issue.
The friction is that these costs don’t arrive evenly. Benefits deductions don’t hit your invoice, but employer-side benefit costs can be priced into the markup once eligibility triggers. PTO accrual can also create a timing mismatch: you see the cost in a later invoice even though the hours that earned it were weeks earlier. If the contract allows “rate adjustments for benefit changes,” the practical risk is budgeting off the first clean month and getting surprised in month two—right when you’re considering adding headcount.
Revised thinking: confirm terms before scaling headcount
By the time you’re thinking about adding five more people, the question isn’t whether the agency can “handle payroll.” It’s whether the price you’re scaling is actually the same price under real conditions: overtime spikes, a holiday week, a job-duty tweak, a location change. That’s when a clean bill rate stops feeling like a number and starts feeling like a set of triggers you may not be tracking.
Before you ramp headcount, it helps to force the terms into a checklist you can reconcile against invoices: which items are fixed in the rate versus pass-through, whether workers’ comp class codes are locked, how unemployment increases get recovered, and what benefits or paid time assumptions are baked into pricing. The practical constraint is timing—get those answers while you still have leverage, not after the hours are worked and the “adjustment” line arrives.