You’re negotiating a term sheet at midnight
The email lands at 11:47 p.m., and the investor wants a signed term sheet by morning so they can “start legal.” There’s a number that looks fair on valuation, but the PDF is dense in the places that matter: preference, conversion, dividends, protective provisions. Counsel is texting in fragments, the board is half-asleep, and the only model you have open is a cap table that assumes common stock simplicity.
The pressure isn’t just speed; it’s the asymmetry. Every defined term quietly rewrites the payoff in scenarios no one wants to dwell on at midnight—mediocre exits, down rounds, or a long grind before liquidity. If you can’t translate each preferred right into “who gets paid, when, and how much,” you’re not really negotiating yet—you’re just accepting a story.
Your expected exit math breaks at liquidation preference
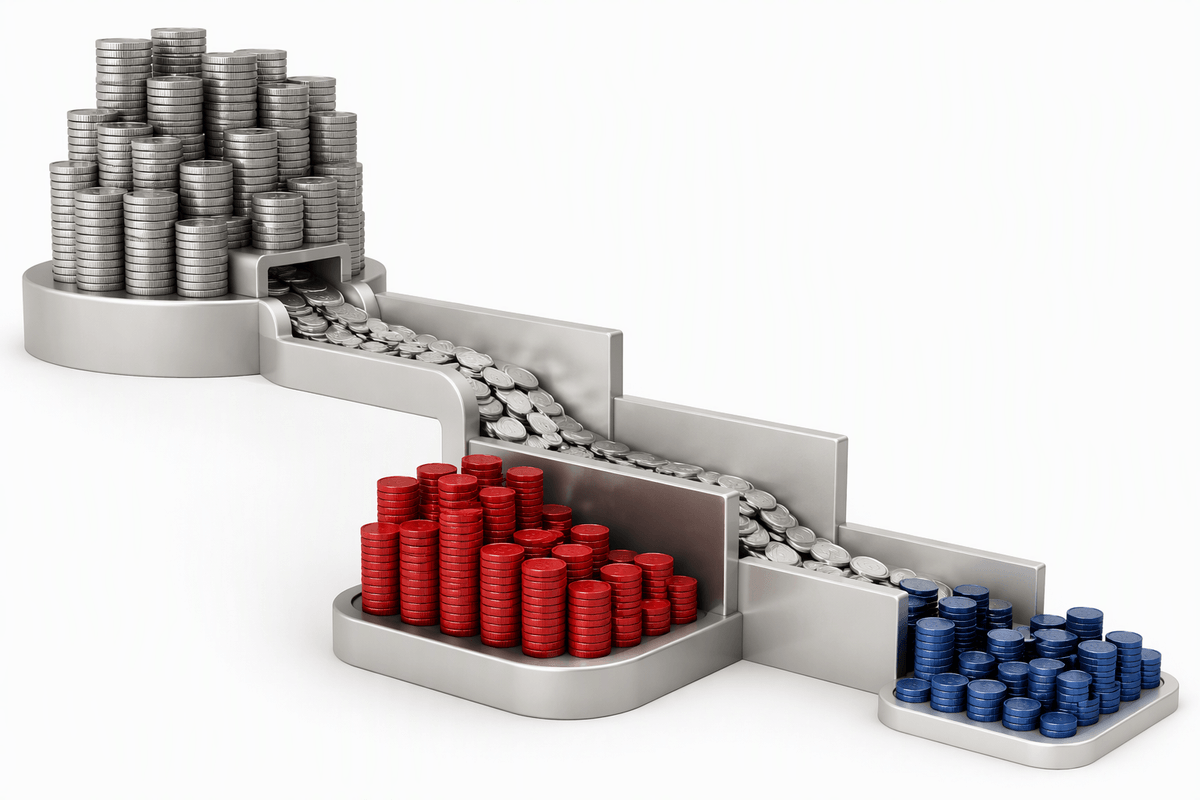
The first place the “story” usually falls apart is the liquidation preference, because it turns your exit from a simple ownership percentage into a payout waterfall. At a glance, “1x non-participating” can look harmless—until you run the numbers on a so-so sale where the preference effectively sits in front of common. Add a multiple (2x) or any participation, and suddenly the valuation you negotiated doesn’t explain what founders and early executives actually take home.
The friction shows up when timing and outcome are mismatched: a decent acquisition offer arrives before a big growth inflection, and the preferred has a guaranteed return path while common only participates after that hurdle is cleared. If there’s an option pool refresh or a second preferred round stacked on top, the “stack” raises the hurdle again. In that moment, the right question isn’t “is the valuation fair,” it’s “at what exit price does common start behaving like the cap table model I’ve been using?”
Conversion rights decide who benefits in big wins
Once you’ve found the exit price where common finally “turns on,” the next surprise is that the preferred may not stay preferred. In a large outcome, investors usually choose between taking the liquidation preference or converting to common to share pro rata. That choice sounds mechanical, but it’s where the real economics live: if the term sheet has a 1x preference and the company sells for far more than invested capital, conversion is typically the better deal for them, and the preference becomes mostly a floor, not a haircut.
The constraint is that conversion is rarely just “yes/no.” Automatic conversion thresholds, IPO conversion rules, and any participation features can shift the breakpoints. A messy cap table makes it worse: multiple preferred series convert at different incentives, and a small misread of “as-converted” ownership can change who benefits from the last dollars of the deal. The practical check is to calculate the investor’s indifference point: at what exit value do they make the same money either way? That number tells you whether your “big win” is actually shared, or quietly optimized.
Dividends look small until time and stacking
After you’ve mapped the conversion breakpoints, dividends are the clause that feels like background noise—until the deal takes longer than planned. The term sheet might say “8% non-cumulative” and everyone moves on, or it might say “cumulative” and you still shrug because 8% of a few million doesn’t sound like the thing that changes a founder outcome. The catch is timing: when liquidity slips from two years to six, that “small” return becomes a real dollar amount that either comes off the top at exit or silently inflates the preference the investor compares against converting.
The pressure point shows up when dividends stack across multiple preferred rounds. If each series accrues (or is “paid in kind” into more preferred), the liquidation preference hurdle rises even if the headline multiple stays at 1x. In a middling acquisition, that extra stack can be the difference between common getting something versus getting washed out. The practical move is to ask how dividends are treated in the payout waterfall: are they cumulative, do they compound, do they accrue on the original issue price or an increased base, and do unpaid amounts sit senior to common at closing.
Anti-dilution triggers when financing plans change
By the time dividends and preference are penciled in, the next fragility is your next round. The deck says “we’ll raise a growth round in 12 months,” but the constraint is the market, not the plan: if revenue misses, or the category cools, you may be taking a down round or a flat round with structure. That’s when anti-dilution stops being a theoretical protection and starts rewriting the ownership math you thought you’d already negotiated.
Broad-based weighted average is usually survivable: it cushions the investor without detonating the cap table, and the dilution is spread across everyone in proportion to how big the down round actually is. Full ratchet is the landmine, because a small down round at a low price can reset conversion as if all prior preferred bought at the new price, effectively pushing the hit into common and the option pool. The practical friction is definitional: what counts as “issued at a lower price,” which issuances are excluded, and whether an option pool increase is treated like dilution that founders eat twice.
Sanity-check scenarios before you sign the docs
At this point the term sheet stops being a list of clauses and turns into three numbers you can’t avoid: the “common turns on” price, the investor’s conversion indifference point, and the fully loaded preference stack after dividends. The sanity check is running those breakpoints against outcomes your team might actually see, not the one heroic exit everyone is mentally anchored to. A $60M sale, a $150M sale, and a $500M sale will usually reveal whether the paper is a floor, a wedge, or a quiet transfer of the middle.
The constraint is time and error rate: you’re doing this while legal is drafting, and small definitional choices change the table. Model at least one down round with your expected option pool refresh and apply the exact anti-dilution formula, then re-run the exit waterfall with and without conversion. If the “down round + modest exit” case pushes common close to zero, don’t argue from vibes—ask which single term (participation, cumulative dividends, seniority, full ratchet, pool increase timing) is creating the cliff and whether it can be softened.
Walk away with a tighter set of questions
When the model finally matches the legal language, the negotiation shifts from “is this standard” to “what happens in the outcomes we might actually live through.” The immediate constraint is that most term sheets still have a few blanks or soft phrases, and those are exactly where economics drift: seniority between series, whether dividends accrue into the preference, whether participation has a cap, whether anti-dilution excludes pool increases or only certain issuances.
Walk away with questions that force a clean spreadsheet answer: “Show me the waterfall at $60M, $150M, and $500M, with all series and dividends included.” “At what price does each series convert, and what triggers automatic conversion?” “If the next round is 20% lower with a pool refresh, what happens to my as-converted ownership?” If they can’t answer quickly, you’ve learned what you’re really being asked to sign.