A diversified portfolio can hide one big bet
An investor can hold a dozen funds and still depend heavily on the same corner of the market. The account statement may look balanced, with different names, managers, and fund categories spread across it. Yet a strong run in one sector can quietly lift everything at once, creating the impression that diversification is working more broadly than it really is. That feels comfortable while prices rise. It becomes harder to ignore when the sector weakens and several holdings fall together.
The risk is not simply owning too much of one fund. It can come from overlapping companies, workplace stock, or a large position tied to a financial goal. A portfolio may therefore be diversified by label but concentrated by economic exposure, leaving less resilience than expected and making any later correction more costly.
The first surprise appears beneath the fund labels
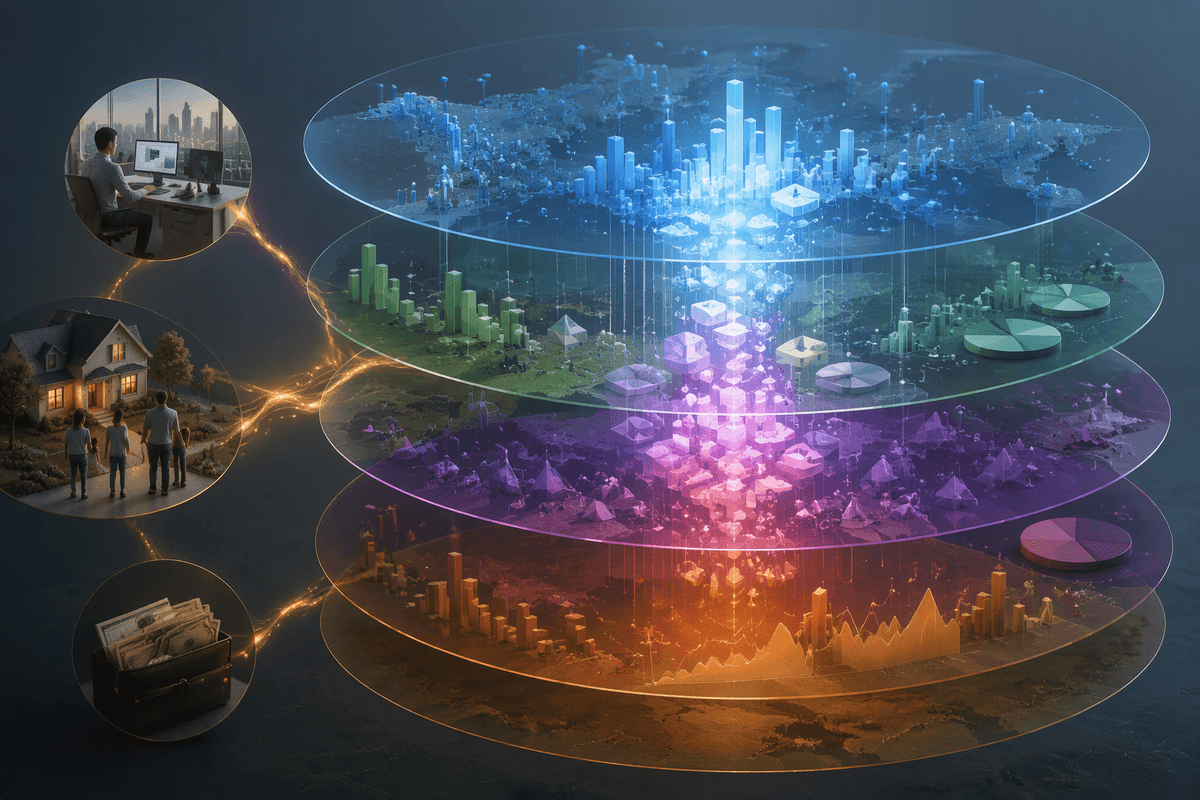
The overlap often appears only after the holdings are reduced to what the businesses actually do. A broad stock fund may already carry substantial exposure to technology, while a dedicated technology fund adds many of the same large companies in a different wrapper. An employer’s shares can deepen that connection if the same industry also provides the household’s income. None of these positions needs to look extreme on its own, but together they can make one sector responsible for a much larger share of the portfolio’s movement.
Fund labels make this harder because they describe strategy, size, or geography rather than the risk that ultimately matters. Two funds with different names may respond to the same interest-rate change, supply disruption, or shift in investor enthusiasm. Checking the largest holdings is a useful first pass, but it can miss smaller positions spread across several accounts. The review also takes time, and fund holdings change, so a snapshot is not a permanent answer. Still, once repeated exposure is visible, the decision becomes less about whether one fund is “diversified” and more about how much of the household’s financial future depends on the same economic outcome.
Map exposure across every account and goal
Once the overlap is visible, the next step is to stop reviewing accounts in isolation. A taxable brokerage account, retirement plan, workplace stock, and cash reserve may serve different purposes, but they still belong to the same household balance sheet. A sector position that seems reasonable in a retirement account can become much larger when combined with company shares held for a future home purchase or education expense. The practical constraint is that account statements rarely present this picture in one place, so the work usually requires collecting holdings, current values, and the purpose of each account.
Mapping exposure also means separating money by time horizon. Funds needed within a few years may not have enough time to recover from a sector decline, even if the long-term investment case remains strong. Retirement assets may tolerate more volatility, but a concentrated position can still create a poor sequence of returns near the point withdrawals begin. Income matters as well: employment tied to the same industry increases household exposure even when the investment account itself appears moderate. After each holding is assigned to a goal, sector, and account type, the trade-off becomes clearer. Reducing the position may create taxes, fees, or missed upside, while leaving it untouched preserves simplicity but accepts greater dependence on one outcome.
There is no universal percentage that means excessive
That clearer picture still does not produce a magic cutoff. A 10% sector allocation may be uncomfortable for someone expecting to use the money soon, while a larger share could be manageable for an investor with decades before retirement, stable income, and few other ties to the industry. The same percentage also behaves differently depending on the sector’s volatility, valuation, and role in the broader portfolio. Treating one number as automatically excessive can create false precision.
A more useful test is whether a decline would force a decision at the worst possible time. If a 30% sector drop would delay a home purchase, reduce planned withdrawals, or make the investor abandon a long-term plan, the exposure may be too large for that goal even if it looks modest on paper. Capacity for loss matters, but so does the ability to tolerate uncertainty without constant changes. Estimating the effect of a bad year, including related holdings and employment income, gives the percentage some meaning. It may show that the position is reasonable, or that a seemingly small concentration leaves too little room for error.
Conviction becomes harder to defend after losses
That test becomes more demanding after a loss. A sector that once seemed easy to hold can look indefensible when it falls faster than the rest of the portfolio, especially if several related positions decline together. The investor may still believe the underlying businesses are sound, but the original reasoning is now competing with a visible reduction in wealth. Selling can feel like discipline, while holding can feel like refusing to admit a mistake. Either reaction may be driven more by recent performance than by the role the exposure plays in the plan.
Losses also expose weaknesses that were less obvious during a strong run. A position may have been justified by long-term growth, yet still be too large for the account, too volatile for the goal, or too closely tied to employment income. The practical constraint is that conviction is difficult to measure once money is needed or confidence has already been shaken. Reviewing the original purpose, expected holding period, and tolerable decline can separate a changed investment case from an uncomfortable but expected downturn. That distinction matters before making a costly move.
Changing course can create costs of its own
Even when the exposure no longer feels comfortable, reducing it immediately can create a different set of problems. Selling in a taxable account may trigger capital-gains taxes, while trading costs, fund spreads, or withdrawal penalties can reduce the benefit of the change. Replacing a concentrated holding with several funds can also add fees and make the portfolio harder to maintain.
Timing creates another constraint. A hurried sale after a sharp decline may lock in losses just before a recovery, while waiting for a rebound can leave the original risk untouched. A gradual shift, new contributions directed elsewhere, or rebalancing during normal portfolio reviews may reduce exposure without turning one decision into a market-timing bet. The right adjustment therefore depends on both the risk being reduced and the cost of reducing it.
Choose a level you can hold through cycles
After weighing those costs, the most useful target is usually not the lowest possible sector exposure. It is a level that can remain in place when prices rise, fall, and move sideways for years. A smaller position may reduce anxiety but also weaken the reason for owning it; a larger one may improve returns in a favorable cycle while making the next downturn harder to endure.
The constraint is behavioral as much as financial. If a 40% decline would trigger an unplanned sale, the position is probably larger than the plan can support, regardless of its expected return. A level that fits the household’s goals, timeline, income risk, and tolerance for loss may still disappoint during some cycles. It offers something more durable: enough conviction to stay invested without letting one sector dictate the outcome.