You hired for skills—then the license bill arrives
The offer letter is signed, the schedule is finally covered, and the first week feels like a win—until someone mentions their renewal is due next month. It’s not a huge number on paper, but it lands at the wrong time: payroll is already set, onboarding costs are fresh, and cash flow is doing its usual small-business wobble. The employee assumes it’s a basic work expense. The manager assumes licensed people “just handle that” the way they always have. Nobody is trying to be difficult; it’s just a gap that didn’t show up in the job ad.
Once the bill is real, it stops being abstract fairness talk and turns into a compensation question with deadlines. If the license lapses, the work can’t be scheduled, and the whole staffing plan takes a hit. If the worker pays, they quietly compare the out-of-pocket cost to their hourly rate and start recalculating whether the job is actually a raise.
What you assumed “normal” coverage would look like
Most teams carry an unspoken “normal” in their heads: if the role requires an active license, the costs must already be baked into the market rate, so the worker handles renewals and CE. Or the opposite: anything that keeps the person eligible to work for you is a business expense, so you reimburse it. The conflict is that both can be true in different shops, and neither assumption shows up on the offer letter. The first renewal bill just forces the policy decision early, usually mid-quarter, when the budget isn’t set up for a new line item.
What usually gets missed is the boundary: license renewal versus optional certifications, CE that can be taken on paid time versus after-hours, and dues or access fees that feel “work-related” but aren’t legally required to hold the license. Then payroll runs into tax treatment: reimbursement under an accountable expense process behaves differently than a flat stipend added to pay. Once those distinctions are named, “normal coverage” stops being a vibe and starts looking like a small compensation plan with rules.
When budgets collide with compliance and scheduling realities
By the time the renewal notice hits, the real constraint is rarely the dollar amount. It’s the calendar. Finance wants predictability, managers want shifts filled, and the licensed worker has a hard stop date where “almost renewed” still means “can’t work.” If the person can’t practice without an active credential, the schedule doesn’t just get inconvenient—it can turn into forced cancellations, overtime, or pulling someone out of their normal role to cover. That’s when a $200–$800 renewal starts behaving like a much larger operational cost.
Compliance pressure makes the budget debate lopsided. Some industries can’t bill, can’t staff certain cases, or can’t meet contract requirements if the license lapses, and “we reimburse later” doesn’t solve the immediate gap. Add CE requirements and the friction shifts again: paying the course fee is one thing, but the time to complete it can collide with peak season, month-end close, or a thin weekend roster. Teams end up choosing between authorizing paid time (visible labor cost) or pushing CE into personal hours (hidden retention cost).
What I see work best is treating renewals and required CE like a continuity risk, not a perk. Once it’s framed that way, the practical questions get sharper: who tracks due dates, what proof is required, what happens if someone forgets, and whether reimbursement timing matches when the cash has to leave the employee’s account. The policy doesn’t need to be generous to be functional, but it does need to match how unforgiving the license clock is.
Choose your policy stance without accidentally underpaying
The moment you decide “we’ll cover it” or “it’s on the professional,” the next risk is simpler: the offer rate quietly becomes wrong. If the role is priced at market assuming the worker pays their own renewal and CE, then adding reimbursement is an actual increase in total comp (and it can widen gaps between tenured staff and new hires). If the role is priced assuming the employer covers required costs, then pushing fees back onto the worker is a pay cut in disguise—especially for hourly staff who feel it immediately when a $400 renewal hits the same month as a lighter schedule.
Most teams land in one of three stances, and each has a predictable failure mode. Full reimbursement for required renewal/CE is clean for compliance, but it needs a cap, timing rules, and a definition of “required” to avoid paying for every résumé upgrade. A flat stipend is easy to budget, but if it’s too low or treated like “extra pay,” it can miss the actual renewal date and still create lapse risk. Baking an estimated annual license/CE amount into wages avoids paperwork, but only works if you revisit the rate when requirements or fees change; otherwise inflation and rule changes turn into accidental underpayment.
Before locking anything in, run one quick reality check: what would a reasonable person think the all-in pay is after typical annual license costs, mandatory CE fees, and the time it takes to complete them? If the answer is “less than what competitors are effectively paying,” the policy is already signaling, even if nobody has complained yet.
The mismatch shows up in retention and morale signals
You don’t usually see the policy mismatch in a spreadsheet first; you see it in behavior. The licensed person stops volunteering for the extra shift, gets slower about picking up call, or suddenly becomes very exact about clock-out times because the “small” renewal bill is sitting on their card. In tighter labor markets, the signal is even simpler: a competitor’s offer doesn’t have to be higher on the hourly rate if it removes the annual surprise and the scramble for CE time.
Morale takes a hit when the rule feels improvized. If one manager reimburses immediately and another says “submit it at month-end,” people read it as favoritism, not process. The timing friction is the quiet killer: reimbursement that arrives two payrolls later still forces the employee to float $300–$800, and that lands differently for hourly staff than for higher-paid professionals. Once that pattern starts, retention risk shows up as “professional development fatigue,” more PTO taken around renewal deadlines, and departures that cite “pay” even when the real complaint was predictability.
Revise the deal: reimbursements, stipends, or pay adjustments
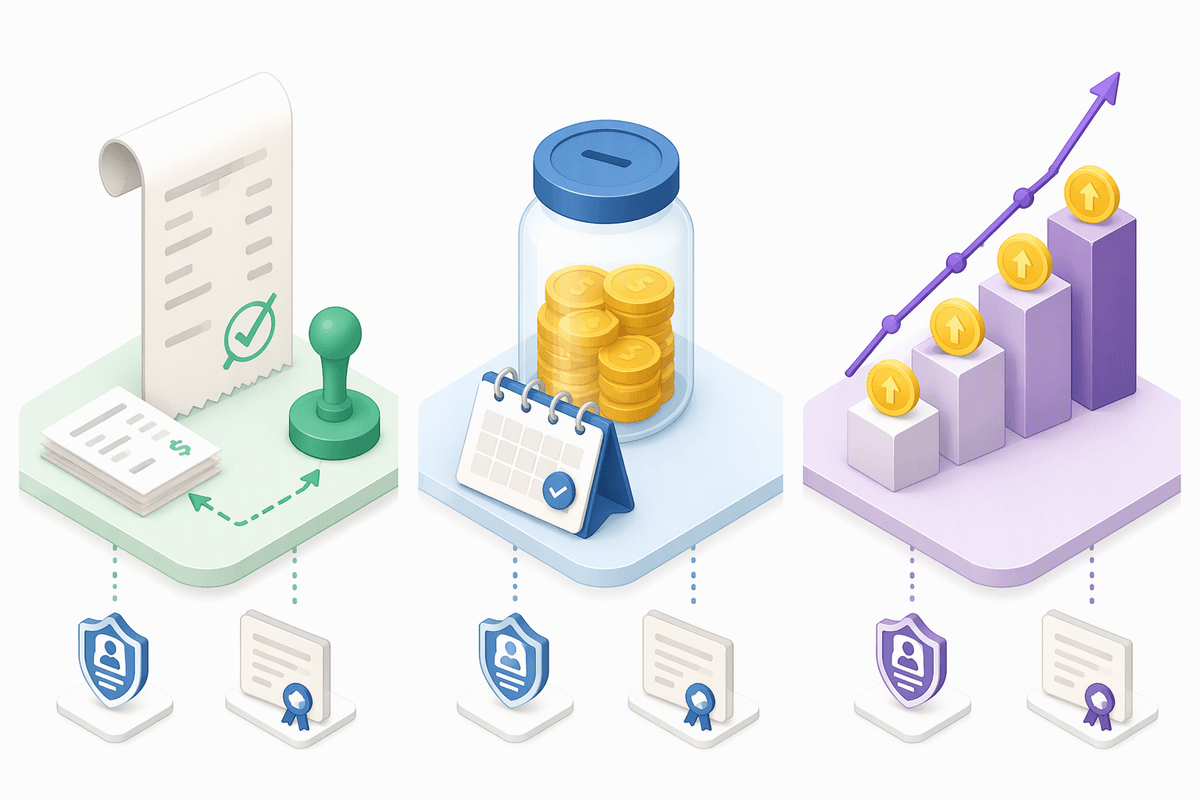
Once the signals start, the fix isn’t a memo—it’s a clean revision to the deal that removes the annual surprise without creating a benefit nobody can administer. Reimbursement is the most defensible when the license is a hard condition of working: pay the renewal and required CE through an accountable expense process, require receipts, and set timing that matches when the cash leaves the employee’s account. The constraint is admin friction, so it only works if someone owns the tracking and approvals don’t stall at month-end.
If you need budget certainty, a stipend can work, but only if it’s explicitly tied to maintaining active status and sized to real costs in your state. The failure mode is a “nice extra” that doesn’t cover the renewal week, leaving lapse risk intact. A wage adjustment is the lowest paperwork option, but it has to be recalibrated when fees or CE hours change; otherwise it quietly decays and turns back into underpayment.
A simple checkpoint list before the next renewal cycle
Before the next renewal window sneaks up, it helps to run a short checkpoint list while there’s still time to change payroll settings and approvals. Confirm what counts as “required” (renewal, mandated CE, background checks) versus optional upgrades, and write it in the same place offers are generated. Price the stance into total compensation on purpose: either document reimbursement rules, set a stipend amount that matches typical state costs, or adjust the base rate and note what it replaces.
Then stress-test the timing. Who tracks due dates, how far in advance reminders go, and whether employees are expected to front the cash. Decide what proof is needed, how fast reimbursements are paid, and what happens if someone misses a deadline and can’t be scheduled. Finally, check equity: are long-tenured staff treated the same as new hires, and does the policy still work if fees rise next year?